Let’s Map Out Your Home Journey
Purchase, refinance and home equity loans for Orlando and Central Florida, from The Woodburn Team at CrossCountry Mortgage in Winter Park.
Purchase, refinance and home equity loans for Orlando and Central Florida, from The Woodburn Team at CrossCountry Mortgage in Winter Park.
Bruce Woodburn NMLS #228431 · CrossCountry Mortgage, LLC NMLS #3029 · 407-869-8830 · Equal Housing Opportunity
⭐⭐⭐⭐⭐
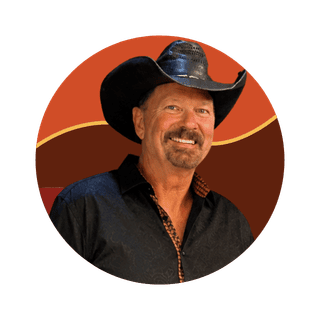
Bruce Woodburn (NMLS #228431) is the branch manager and mortgage loan originator Central Florida knows as The Loan Arranger. He has been arranging home loans for Orlando-area families since 1989, started The Woodburn Team in 1994 and joined CrossCountry Mortgage in 2017 — through the boom, through the crash, through all of it. The office is at 2729 W. Fairbanks Ave. in Winter Park, just north of downtown Orlando, and the door is open.
So let’s do this the right way.
Bruce Woodburn has hosted mortgage and real estate radio in Orlando for more than 25 years. Tune in to “Loan Arranger Radio” on WDBO 107.3 FM / 580 AM Saturdays at 12pm and on 102.5 The Bone in Tampa Saturdays at 11am. Off the air, he teaches first-time homebuyer classes, Realtor continuing-education courses and construction loan workshops across Central Florida.



Already own a home
Still unsure which path is right? → Call Bruce and the team at 407-869-8830.
Compare Orlando mortgage lenders on four things:
✔️ Licensing you can verify. Look up any loan officer’s NMLS ID at nmlsconsumeraccess.org.
✔️ The full cost, not only the rate. Ask each lender for a Loan Estimate on the same day for the same loan, then compare the interest rate, APR and closing costs side by side.
✔️ Reviews you can trace. Look for reviews on a public platform such as Google, where every review is visible.
✔️ Who handles the loan, and whether it closes on time. Ask if one loan officer stays with the file from pre-approval to closing, and ask for the lender’s on-time closing record. A missed closing date can cost a buyer the house.
Here is how we answer each one. Bruce Woodburn is NMLS #228431 and CrossCountry Mortgage, LLC is NMLS #3029. We provide a Loan Estimate to compare. Our client reviews are public on Google. And on eligible purchase loans, The Loan Arranger Advantage™ puts our on-time closing commitment in writing. Terms and exclusions apply.
We check every box above — verifiable licensing, real traceable reviews, and a closing record backed by our guarantee.
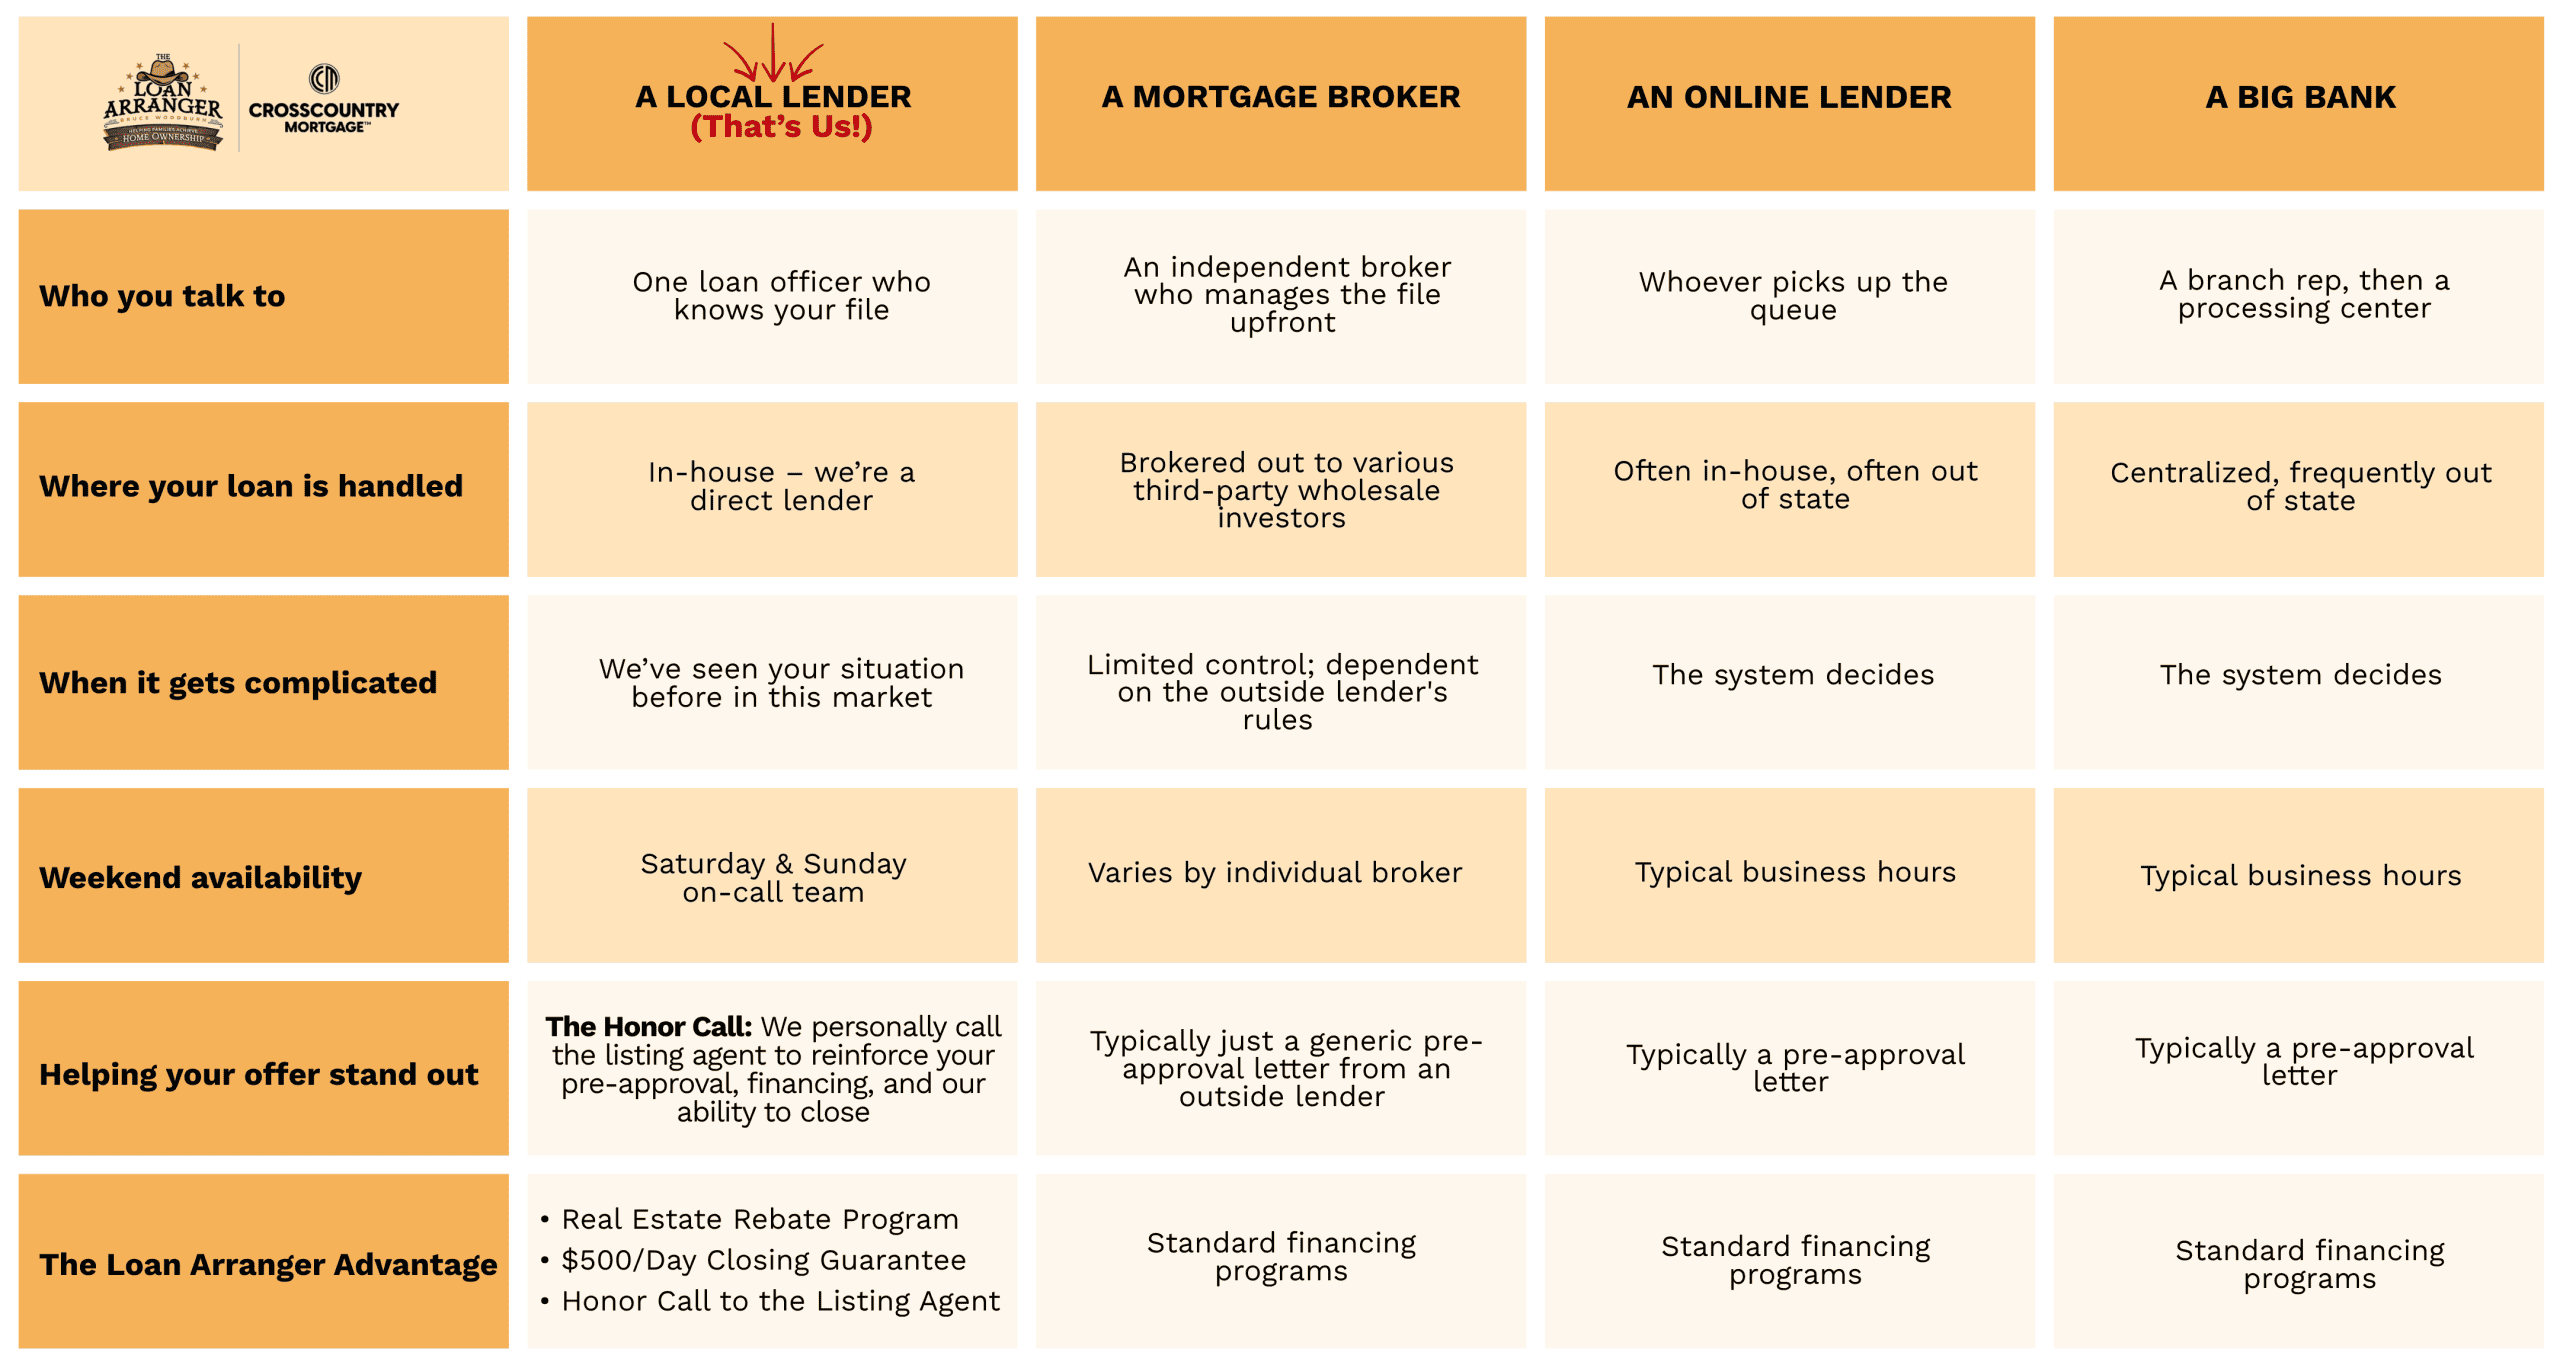
When you make an offer, we don’t just send a pre-approval letter and hope for the best. We personally call the listing agent to introduce ourselves, reinforce the strength of your pre-approval, answer questions about your financing, and explain why they can have confidence in our ability to get you to closing. In a competitive situation, that extra confidence can help your offer stand out.
Online lenders advertise convenience — right up until something goes sideways two weeks before closing. And we’ll be straight with you: our application is fully digital and takes minutes, same as theirs. The difference isn’t the technology. The difference is who picks up the phone after you apply.
• One loan officer, start to finish. No call centers. No hand-offs. Somebody who knows your name and your file.
• Somebody answers on the weekend. You find the house Saturday afternoon; many lenders call back on Monday. We run a Saturday and Sunday on-call team, because Orlando homes don’t wait for business hours and neither should your approval letter.
• We’re a direct lender. Your loan is underwritten in-house, which is what makes a Fast Track closing possible on a clean, complete file.
• More ways to say yes. When another lender has already said no, we still want to see the file. We’ve found a path on plenty of them, not because of a magic rate, but because we know which door to knock on. Not every file can be approved, and we’ll say so early.
All loans subject to underwriting approval. Certain restrictions apply. Closing timelines depend on complete documentation, appraisal, title and third-party turn times.
• A personal consultation before you tour a single house. We build a financing plan around your real life. Whether you rely on tip and overtime income near the parks, have a travel-nurse contract at AdventHealth, teach in Seminole County, or work for yourself, we know how to handle it. Every situation requires a specific approach, and we sort out the details on day one so you don’t hit a roadblock on day 25.
• A fully underwritten approval, so you compete like a cash buyer. A real underwriter reviews your actual documents up front — not a website that skims your credit and prints a letter. When a seller is weighing multiple offers, that can be the difference between “we’ll consider it” and “it’s yours.”
• Tuesday updates and milestone videos, all the way to the keys. Every Tuesday you get an email telling you exactly where your loan stands. At every milestone — pre-approval, into underwriting, conditional approval, clear to close — you get a note plus a short video from Bruce explaining what just happened and what’s next.
The 20%-down rule is a myth for most buyers today. Common minimums for qualified buyers:
– Conventional loans: as little as 3% down
– FHA loans: 3.5% down
– VA loans: no down payment for eligible veterans and service members
Income-qualified first-time buyers in eligible occupations, including school staff, health care workers and first responders, may also qualify for Florida Hometown Heroes. It provides up to $35,000 toward the down payment and closing costs as a 0% second mortgage, repaid when the home is sold, refinanced or no longer the primary residence. Funding is limited and first come, first served, and every past round has run out.
A pre-approval shows which of these fit your situation.
Eligibility, income limits and funding availability are set by the Florida Housing Finance Corporation and subject to change.
Lower payment, shorter term, or cash out of your equity for renovations or debt consolidation — we’ll run all of it with you. And if refinancing doesn’t make sense for your situation, we’ll tell you so. That’s not us being noble; it’s why people come back and send their friends.
Want to keep your current mortgage rate? A HELOC borrows against your equity without replacing your first mortgage.
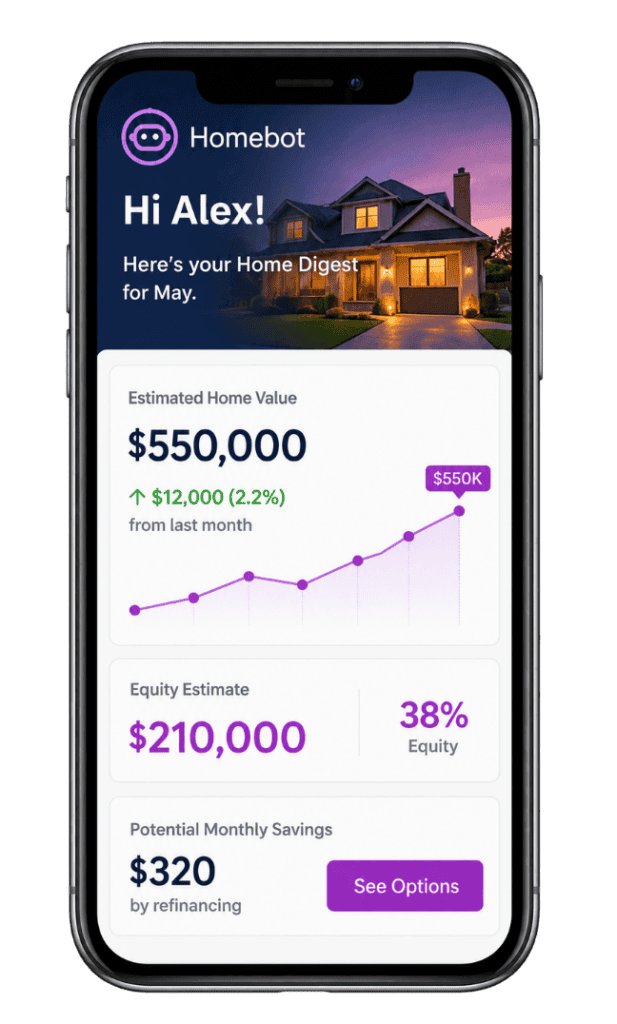
Sign up for the Home Digest and get a monthly email built around your home:
It’s free, and it stays between you and our team. Many home-search sites pass your contact details to agents and lenders who advertise there. Ours doesn’t: your information isn’t sold to outside agents or lenders, and the only people who follow up are The Woodburn Team.
Home values shown are automated estimates, not an appraisal.
You don’t need a perfect credit score to reach out. You don’t need your down payment saved. You don’t even need to be sure you’re buying this year. You just need somebody in Orlando who’ll shoot straight with you.
Call Bruce and the team at 407-869-8830, or 407-250-9144 after hours and on weekends. The office is at 2729 W. Fairbanks Ave., Winter Park, FL 32789.
So let’s get started. The next stage of your life is waiting.
A local team knows this market: which condo buildings are warrantable, how Florida insurance affects your approval and which builders move fast. You also get one person who’s still there when something goes sideways.
Pre-qualification is an estimate based on what you told us. Pre-approval means we’ve verified your credit, income and assets, which makes your offer far stronger with a seller. Our four-hour pre-approval is fully underwritten.
A direct lender. Your loan is processed and underwritten in-house, which gives us control over the timeline instead of waiting on somebody else’s.
No. Our office is in Winter Park, and we serve buyers throughout Orlando and Central Florida, including Orange, Seminole, Osceola and Lake counties. We also lend in all 50 states through CrossCountry Mortgage.
Yes. The application is fully digital if you want it to be, but this is a big life event. Come to the Winter Park office and go through it face to face. Not local? We do Zoom appointments, too.
Yes. Document uploads run through CrossCountry Mortgage’s encrypted portal. We will never ask you to send bank statements, W-2s or tax returns by unencrypted email.
Every one, through the Nationwide Multistate Licensing System. Bruce Woodburn is NMLS #228431. Look any of us up at nmlsconsumeraccess.org, and do that with any lender you’re considering, not just us.